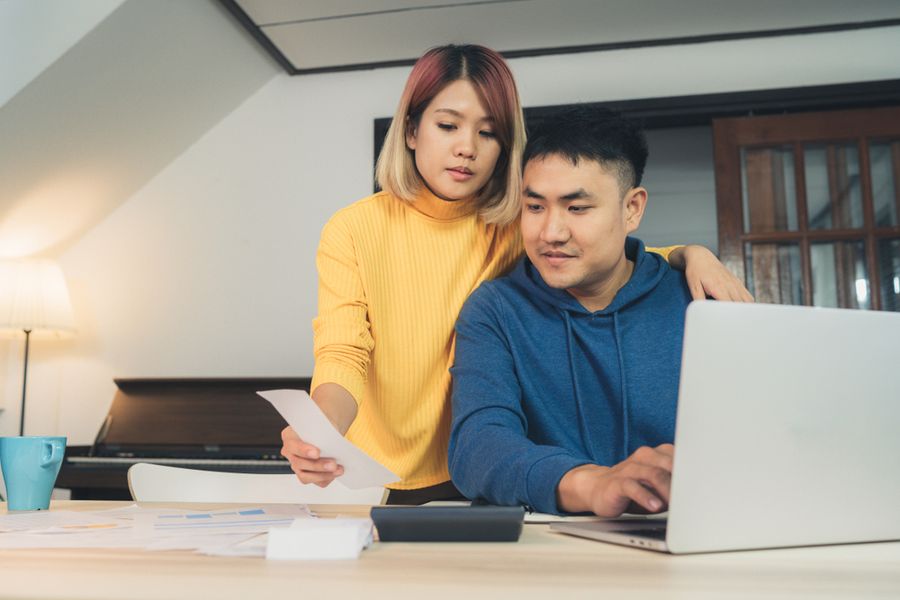
Combining finances with a partner can simplify household money management, but it also creates new responsibilities. Before opening joint accounts or redirecting paychecks, both people should understand what they are bringing into the arrangement and how they want shared money to work. A thoughtful approach can reduce surprises around debt, spending, savings, and access to funds. A few crucial steps can help couples build a system that feels transparent, practical, and easier to maintain.
1. Share the Full Financial Picture
Start by laying out the basics: income, recurring expenses, savings, debts, loans, credit cards, and major financial obligations. The purpose is not to judge past decisions but to make sure both partners understand the household's starting point before money begins moving into shared accounts.
Reviewing credit reports can help uncover accounts, balances, or reporting errors that might otherwise be overlooked. Consumers can currently review their reports from the three nationwide credit bureaus without charge each week, and checking your own report does not affect your credit scores. It can also be useful to compare regular bills and financial commitments so neither person discovers an unexpected obligation after finances have already been combined.
This conversation should include financial responsibilities outside the household as well. Regular support for relatives, child support, student loans, or other commitments may influence how much each person can realistically contribute toward shared expenses.
2. Agree on Shared Goals Before Choosing Accounts
Combining money is easier when both people know what they are trying to accomplish. Discuss immediate priorities such as building an emergency fund, paying down debt, or saving for a move, as well as longer-term goals such as buying a home or preparing for retirement.
Writing down the goals can force useful decisions about timing and priority. If both partners want to save for a home but one also wants to eliminate credit card debt first, the conversation should address how money will be divided between those objectives. Financial planning tools commonly begin with identifying goals, tracking income and bills, and making deliberate decisions about saving and debt repayment.
Do not assume that a shared goal automatically means identical spending preferences. Agreeing on the destination is only the first step; couples also need to decide how quickly they want to get there and what trade-offs they are willing to make.
3. Decide What Will Actually Become Joint
Combining finances does not have to mean merging every account. Some couples deposit all income into joint accounts, while others maintain individual accounts and create one shared account for household expenses. A hybrid approach can also allow each person to retain some personal spending money while contributing to shared goals.
Before opening a joint bank account, understand what joint ownership means. Joint account holders generally have equal withdrawal rights, and each co-owner's interests in qualifying joint accounts at the same insured bank are covered up to the applicable deposit-insurance limit. Because a joint owner may be able to withdraw money independently, adding someone to an account should be treated as a significant financial decision rather than an administrative convenience.
Discuss which accounts will remain separate as well. Personal emergency savings, inherited assets, existing investments, or certain debt payments may warrant separate handling depending on the couple's circumstances and legal considerations.
4. Set Rules for Spending, Debt, and Credit
Once shared accounts are involved, couples need clear expectations around how money can be used. Decide which expenses will come from joint funds, whether either person needs to discuss purchases above a certain amount, and how discretionary spending will be handled.
Debt requires similar clarity. Combining household finances does not automatically make every existing debt legally joint, but debt payments can still affect the shared budget. Both partners should understand the balances, required payments, interest rates, and repayment priorities they are agreeing to accommodate.
Credit accounts deserve particular attention because account ownership and authorized-user status are not the same thing. Credit reports can show whether someone is reported as an owner or merely an authorized user, so reviewing reports before making major credit decisions can help catch misunderstandings or inaccuracies.
5. Test the System Before Fully Committing
There is no requirement to merge everything at once. A trial period can reveal problems before the arrangement becomes difficult to unwind. One option is to open a shared checking account for household bills while continuing to receive income and manage other funds separately.
Run the system for several months and pay attention to what causes friction. Perhaps the contribution amounts feel uneven, one person is doing all the financial administration, or the shared account regularly runs too low before bills arrive. Those problems are easier to address when the arrangement is still relatively simple.
Schedule regular conversations rather than waiting until something goes wrong. Discussing money decisions in advance, documenting agreements, and identifying next steps can make financial arrangements clearer and reduce misunderstandings. The exact system can change as income, expenses, and relationships evolve.
Combine Finances With a Plan, Not an Assumption
Combining finances is not just a matter of opening a joint checking account. It requires disclosure, shared priorities, clear boundaries, and agreement about how everyday decisions will be made.
Start by understanding each other's finances, decide what goals the household will pursue, choose deliberately which accounts become joint, establish rules for spending and debt, and test the arrangement before expanding it. A good financial system should make shared responsibilities easier to manage without leaving either partner confused about where the money goes or who is responsible for what.