An emergency financial plan should address more than savings and insurance. It should also answer a difficult practical question: who could handle your financial affairs if illness, injury, or another emergency temporarily or permanently prevented you from doing so? A financial power of attorney can provide that authority in advance. Used carefully, it can help keep bills paid, accounts managed, and important financial tasks moving when you are unable to handle them yourself.
Understand What a Financial Power of Attorney Does
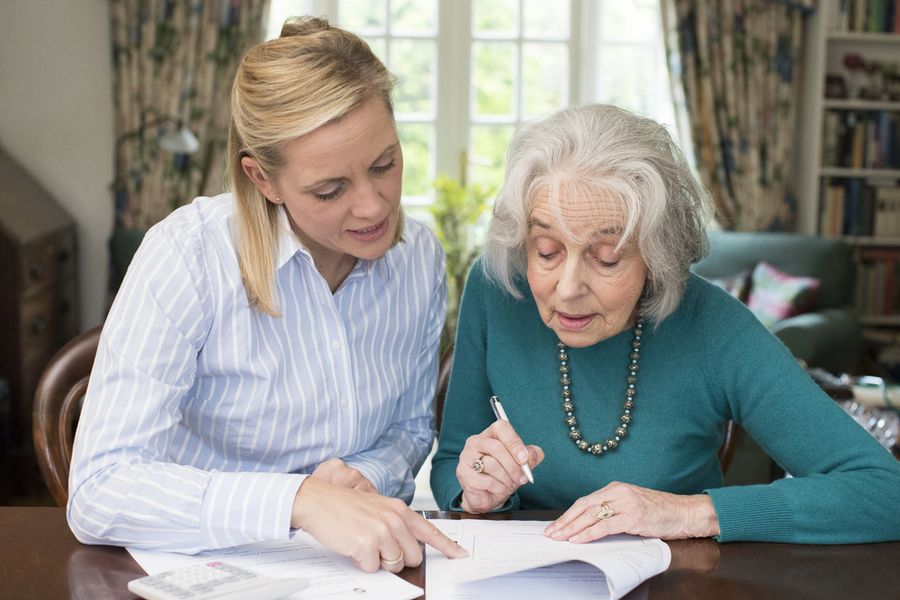
A financial power of attorney, or POA, is a legal document that authorizes another person, called an agent or attorney-in-fact, to act on your behalf. Depending on the authority granted, an agent might be able to pay bills, manage bank accounts, handle property, or complete other financial transactions.
For emergency planning, a durable financial POA can be particularly important because it is designed to remain effective if the person who created it later becomes incapacitated. A financial POA is separate from a health care power of attorney, which concerns medical decisions rather than management of money and property.
Decide When the Authority Should Take Effect
Not every financial POA operates in exactly the same way. Some documents give the agent authority as soon as they are properly executed, while others are designed so that authority begins only after a specified event, such as the principal becoming incapacitated. These are sometimes called "springing" powers of attorney.
Because rules governing powers of attorney differ among states, the document needs to comply with the law where it will be used. States also differ in their treatment of durability, execution requirements, and other provisions. Working with an attorney familiar with your state's requirements can help ensure that the document works the way you intend instead of discovering a problem during an emergency.
Choose the Agent Very Carefully
A financial POA can give another person substantial control over your money. The agent may be able to withdraw funds, pay expenses, manage investments, or take other actions depending on the document. That makes trustworthiness at least as important as financial knowledge.
Choose someone who is responsible, organized, willing to perform the job, and capable of following your instructions. An agent acting under a POA has fiduciary responsibilities, including acting in your interests, managing property carefully, keeping your assets separate from their own, and maintaining accurate records.
It can also be sensible to name a successor agent in case your first choice is unavailable when an emergency occurs. Discuss the role with anyone you intend to appoint rather than assuming that person will be willing or prepared to take it on.
Define the Powers the Agent Will Need
A useful emergency POA should give the agent enough authority to handle foreseeable problems without automatically granting powers you do not want someone else to have.
Consider the financial responsibilities that would need attention if you became unavailable for several weeks or months. These might include paying a mortgage or rent, accessing checking accounts, dealing with insurance, managing investments, handling property expenses, or communicating with financial institutions. Certain unusually broad actions, such as making gifts or changing beneficiary arrangements, may require specific authorization and deserve particularly careful consideration.
The goal is not necessarily to give the agent every imaginable power. It is to ensure that the document matches the responsibilities the agent might realistically need to assume.
Make Sure the Document Can Be Used
A legally valid document is much less helpful if nobody can find it during an emergency. Store the original or an appropriately accessible copy somewhere secure, and make sure your agent knows how to obtain it when necessary.
It can also be worthwhile to ask banks, brokerage firms, and other important financial institutions how they handle outside powers of attorney before an emergency occurs. A bank can allow an agent acting under a valid POA to conduct transactions on the account while the account itself remains in the principal's name.
Advance preparation can reduce the chance that your agent spends valuable time locating paperwork or determining which institution needs which documents while bills and other obligations are already coming due.
Connect the POA to the Rest of Your Emergency Plan
A financial POA works better when it is supported by organized financial information. Your agent may have legal authority to act but still need to know which bills exist, where accounts are held, what insurance policies are active, and which financial obligations require immediate attention.
Create an inventory of important accounts, recurring expenses, debts, insurance policies, financial advisers, and other useful contacts. Keep sensitive credentials secure rather than casually including passwords in an easily accessible planning document. You can also provide a trusted person with a general overview of your finances so that someone knows where to begin if you become unable to manage them yourself.
Review the plan periodically, particularly after major changes such as marriage, divorce, relocation, the death of an appointed agent, or significant changes in your finances.
Prepare Before the Emergency Happens
A financial power of attorney is most valuable when it is created before anyone urgently needs it. Without advance planning, family members may face greater difficulty obtaining authority to manage someone's finances after that person becomes incapacitated, potentially requiring a court proceeding.
The strongest emergency plan combines a properly prepared POA with a trustworthy agent, clearly defined authority, accessible documents, and organized financial information. Putting those pieces in place while you are able to make deliberate decisions can make an already difficult emergency considerably easier to manage.